
Justin C. Freeman
Chief Credit Officer, Bank CMG
Leading Credit through Responsible Growth
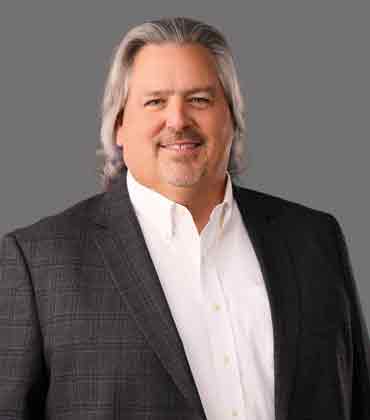
A veteran credit leader, Justin C. Freeman brings more than three decades of experience across lending, consulting and credit risk roles. His background spans from community banks to large national institutions.
At many banks, a chief credit officer is pictured sitting in the back of the room, weighing risk and invariably saying no. Justin C. Freeman, chief credit officer of Bank CMG, sees the job differently. To him, protecting Bank CMG’s loan portfolio and helping the bank grow are two halves of the same equation. He acts as the bridge between the bank’s lenders and its board, building loan structures that protect Bank CMG while giving borrowers the financing to grow. This growth, he says, circles back to the community Bank CMG serves.
Freeman cut his teeth in credit in the mid-1990s, going through Comerica Bank’s training program before moving through several lending roles. A consulting stint at Point Moran led to his first chief credit officer role at a client, where he spent five years transforming a small credit function into a full department of analysts and documentation specialists.
From there, he returned to consulting, joining what was then McGladrey, now RSM, where he spent more than 12 years, rising to lead its national credit risk practice. He worked with institutions ranging from small community banks to some of the largest in the world. The transition to join Bank CMG as chief credit officer felt like a natural step.
Building a New Credit Culture
Bank CMG grew from about USD 500 million to approximately USD 1.5 billion in assets during Freeman’s first year through a mix of acquisition and organic growth. He used that momentum to overhaul the credit department and introduce a new credit policy focused on supporting growth while maintaining disciplined lending standards.
“We want to be their deposit function. We want to be their wealth management function. We want to be their lender,” says Freeman. “We really want to become a trusted advisor with our clients.”
Becoming a trusted advisor starts with knowing the borrower beyond the numbers on a loan application and understanding the industry in which it operates. Freeman still leans on the five Cs of credit—character, capacity, capital, collateral and conditions—while focusing particularly on cash flow and the ability to repay. That understanding helps him structure credit that works for both the bank and the borrower.
" The chief credit officer is still the North Pole, so to speak, in terms of credit and establishing the culture for the bank. "
Growth tests this balance. Leading with price or agreeing to whatever a borrower asks can make growth look easy, but it can also increase losses when poor decisions creep into underwriting. Freeman's role is to surface those risks and work with the business side to identify appropriate ways to mitigate them.
Freeman has spent the past year putting Bank CMG’s client data to work, building early-warning indicators for borrower distress, sharpening stress testing and tracking concentrations that inform growth decisions. He does not expect commercial lending underwriting and decisioning to become fully automated. Ownership structures, borrower relationships and loan negotiations still require human interaction and judgment.
Developing the Next Generation
Real-time mentoring anchors the training program Freeman helped build at Bank CMG, letting junior analysts make decisions in a safe environment backed by senior review. He credits part of that approach to his own early willingness to say yes to unfamiliar work and stay curious.
Knowledge sharing runs both ways, giving the credit team access to senior management and decades of market experience. Freeman also expects the role to expand beyond the loan portfolio. A broader view of the economy, he says, will need to be distilled into guidance for lenders and the board.
“Know that you’re not going to know everything and that you need to be on a continual learning path, not just about credit risk, but about banking in general, as well as the overall economy,” he says.
From building a credit department to leading a national credit risk practice and shaping Bank CMG’s credit culture, Freeman has carried that philosophy throughout his career. His recognition among the Top 10 Chief Credit Officers of 2026 marks another chapter in a career built on responsible growth, sound judgment and continual learning.
