
Steve Min
Chief Credit Officer, Credit One Bank
Expanding Credit Access through Data and Decisioning
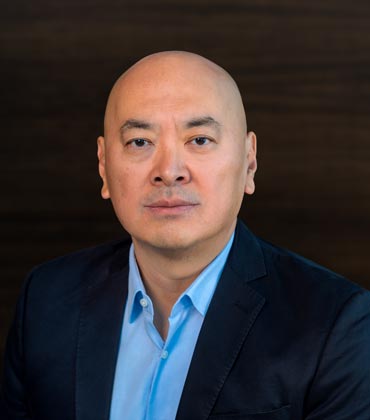
Steve Min is a finance leader with over 20 years of experience across financial services, credit risk and portfolio management. At Credit One Bank, he oversees the risk involved in lending decisions, combining data-driven credit strategies with a focus on compliance and customer outcomes.
Expanding Credit beyond Traditional Boundaries
Min believes that basic credit is essential to everyday activities. As an immigrant, he remembers how his parents’ first credit card helped them secure car loans and a mortgage, shaping his belief that credit can be life-changing. He focuses on consumers whom larger banks underserve because of less-than-perfect credit histories. They are often affected by unexpected life events rather than an unwillingness to repay.
53 percent of customers booked into Credit One’s card portfolio had either no credit card or only one when they came to us. Its business model is designed to provide them with access to credit, education and tools to help rebuild their credit profiles. Providing access to credit must come with the education to manage credit responsibly. Credit education is something the bank is deeply invested in through its advertising campaigns, Keys to Credit section of the website and iconic Credit Wrecker characters that teach what not to do. Its newly launched Credit One Bank Credit Tip Off Tour provides credit education events in college campuses.
Min combines traditional credit and behavioral data with ongoing R&D into new data sources to expand access to credit. Credit One expanded its credit profile to serve these higher-risk consumers, accepting some portfolio trade-offs to grow the market. Despite serving them, its loss rates are relatively less volatile than those of prime borrowers.
Moving Beyond Linear Risk Models
According to Min, one of the challenges in modern credit decisioning is balancing newer modeling techniques with traditional principles, particularly the expectation that relationships between attributes and risk should be linear. More advanced techniques recognize that these relationships can be nonlinear and can change direction across different ranges.
These techniques also reveal interaction effects, where individual attributes may have limited predictive value but become meaningful when considered together. Advances in technology and computational power made it possible to identify these complex relationships. Machine-learning methods like XGBoost and Random Forest have also become increasingly common in credit decisioning.
Min applies these models across Credit One’s decisioning processes. The focus is on combining models and attributes, incorporating additional information to make accurate credit decisions. He believes the industry will move toward more precise credit decisions about who to lend to and how much to lend while continuing to balance risk and fair lending considerations.
Min also examines customer behavior, including ‘micro events’ and account-usage changes that may signal financial stress. Accounts with the same credit score can perform differently depending on behavioral factors like autopay and transaction velocity.
Leading through Collaboration
Min believes empowering people is essential to effective leadership. At Credit One, he empowers risk teams to make lending decisions, rather than pushing decisions upward.
For Min, long-term professional success comes down to collaboration, capability and intellectual curiosity. As professionals become more senior, he believes the how becomes increasingly important because it differentiates people, builds their professional reputation and helps them move across an organization. Intellectual curiosity and capability, meanwhile, help them solve problems and remain effective.
Advice for Emerging Finance Leaders
Min believes career growth should be viewed as a career lattice rather than a ladder. Growth can mean moving up, down or in different directions. The key is to continually look for opportunities to develop new skills, stepping outside your comfort zone.
He deliberately pursued roles outside his comfort zone to broaden his skills and perspective. His experience managing fraud taught him to work within an area marked by urgency and emotion, while a marketing role gave him a broader understanding of how the business and P&L operate. Together, those experiences helped him become a more well-rounded leader within financial services.
