
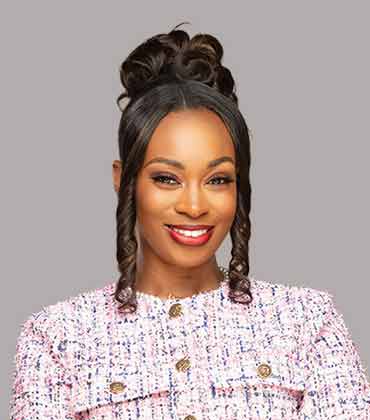
 Dr. Bill Winston, Founder
He eventually left IBM after what he describes as a call to preach and teach, becoming a pastor. As his church grew, so did his conviction that ministry and economic empowerment were connected.
That conviction took shape when a corporate executive asked what Winston could do to help Black male youth in Chicago. He returned seven days later with a program that received $40,000 in funding to start. The program continued for two years and received further financial support during that time. The young people learned basic mathematics, business and commerce, selling eggs in their neighborhoods and opening bank accounts. They were taught how to become entrepreneurs.
That youth program eventually became the foundation for the start of the Joseph Business School five years later, extending Winston’s focus from teaching young people about money to equipping entrepreneurs to build businesses. The school eventually expanded across the United States and internationally.
The same idea shaped his next major venture: a bank intended to help the Christian community build greater economic capacity and to help entrepreneurs find access to capital to start and scale their businesses. But the 2009 financial crisis put the institution under severe pressure, and after several years Winston ultimately had to let it go.
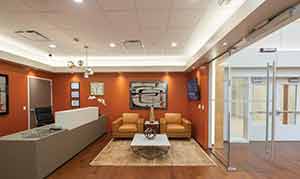 The setback did not change the mission. It changed the vehicle. That vehicle became Joseph Wealth Management, built around Winston’s vision of creating generational wealth and helping close the wealth gap. Rather than assuming clients already understand financial markets or have accumulated substantial wealth, the firm helps them understand how capital works, manage their investments and make informed decisions about their financial future.
For many prospective clients, that education is essential. Some have limited income; others have heard enough stories about market losses to regard investing as risky, inaccessible or simply not meant for them. Joseph Wealth Management combines investment management, financial education and values-based planning to help clients understand what they own, why they own it and what their wealth is intended to accomplish.
The firm's goalis to reach $1 billion in assets under management to help individuals, families and communities develop the knowledge and capacity to create, manage and deploy wealth.
Teaching People How Wealth Works
Traditional wealth management generally assumes that the client has already crossed a certain threshold of financial sophistication or accumulated assets. The advisor's job is then to optimize what exists.
Joseph Wealth Management sees an additional hurdle: There are people with the capacity to build wealth who may never become investors because financial markets feel inaccessible, risky or intimidating.
Winston describes encountering clients who have limited incomes and little experience with investing. Some have heard enough stories about market losses to distrust the stock market entirely. Others simply have never been shown how investment capital can become a resource for a child's education, a retirement plan or a family's future.
For the firm, education is therefore not an add-on to wealth management; it is part of the relationship itself. The firm uses client conversations, financial education and other educational platforms to make investing more understandable while connecting financial decisions to broader principles of stewardship.
“Education is the biggest thing,” Winston says, describing the firm's approach to taking away the intimidation surrounding financial markets. “Our goal is to help clients connect what they own and why they own it to concrete objectives such as education, retirement, family security, legacy and future opportunity.”
Before constructing a portfolio, the team considers a client's goals, time horizon, income requirements, liquidity needs, tax considerations, investment experience and willingness to accept risk. That process resembles the disciplined discovery process found throughout professional wealth management. What it adds is an explicit conversation about purpose: what the client wants their wealth to accomplish, who they want it to benefit and what responsibilities they want it to support.
The firm's investment philosophy remains grounded in familiar concepts such as diversification, asset allocation, liquidity, inflation, taxes, risk and long-term discipline. Faith does not replace financial analysis. Rather, it provides a values framework through which financial decisions can be considered.
Where Faith Meets the Financial Plan
Joseph Wealth Management's Christian Faith Identity is more than a marketing label, but neither is it presented as a substitute for conventional financial practice. The firm describes its approach as biblical stewardship, a concept centered on managing resources responsibly, preparing for the future and using wealth to serve others. For one client, that could mean funding a child's education. For another, it could mean supporting ministry or preparing the next generation to manage an inheritance.
-
Education is the biggest thing. Our goal is to help clients connect what they own and why they own it to concrete objectives such as education, retirement, family security, legacy and future opportunity.
“We want clients to understand their plan well enough to participate confidently in the decision-making process,” says Boma.
The philosophy also changes the advisor-client relationship: the advisor is not simply positioned as the person with the answers, but as a guide helping clients understand the decisions they are making.
One expression of that philosophy is the Joseph Storehouse Treasury Program, which takes its name from the biblical account of Joseph preparing for years of famine by storing resources during years of abundance. The program focuses on U.S. Treasury securities and is intended for conservative objectives such as capital preservation, liquidity, planned expenses or future obligations. Its role is to provide a conservative reserve strategy for clients whose circumstances make capital preservation and planned future needs priorities. The team considers factors including the timing of anticipated expenses, liquidity requirements, risk tolerance and how much of a client's wealth should be allocated to reserves. Selling Treasury securities before maturity can also result in a gain or loss.
The biblical story provides the language for a familiar financial principle: prepare during periods of abundance so that resources are available when future needs arise.
The Portfolio Is Only One Part of the Mission
Joseph Wealth Management's ambitions extend beyond what happens inside a brokerage account. The company describes a model of “doing business while doing good,” directing part of its fees toward community initiatives. Those efforts include financial-literacy work in prisons and jails through the RISE prison ministry, as well as support for the Joseph Business School, a four-month entrepreneurship program that Dr. Winston founded over 25 years ago to help people move from the incubator stage toward building viable businesses.
The model creates a direct connection between the client's financial activity and the firm's community mission: a portion of fees supports programs designed to expand financial literacy, entrepreneurship and economic opportunity.
Boma describes the ambition as a model in which clients are not only investing in their own financial future but also contributing to efforts designed to strengthen their communities.
That proposition is particularly relevant to the firm’s broader focus on closing the wealth gap. The company sees investment participation as one part of a larger economic equation: who has access to financial knowledge, who participates in investment markets, who builds businesses and who has the opportunity to pass both assets and financial capability to the next generation.
The idea also connects Joseph Wealth Management to the entrepreneurial ecosystem developed around the Joseph Business School. Teaching someone how to start and scale a business and teaching that person how to manage the wealth created by the business are treated as parts of the same continuum.
That is perhaps the most interesting aspect of its evolution. The company did not begin with a narrow thesis about portfolio construction. Its roots are in education, entrepreneurship, ministry and economic empowerment. Wealth management became another mechanism for pursuing those goals.
Winston envisions a financially educated faith community functioning as an economic force in its own right. In his view, if enough people within that community understood how to create, invest and deploy capital, the collective effect could extend well beyond individual families. Churches could become less dependent on borrowing, missions could be better financed, and resources could be directed toward helping communities and those in need.
It is a vision of the church not simply as a place of worship, but as a community with the financial capacity to invest in its own future and contribute to the future of others.
Joseph Wealth Management is betting that financial knowledge can itself become a form of capital. That philosophy also informs how the firm looks at a rapidly changing investment landscape. Boma points to artificial intelligence as an area investors should understand—not simply through the headline companies associated with AI, but through the infrastructure required to support its growth. Data centers, energy and other underlying infrastructure could become increasingly important as AI reshapes industries and demands new levels of computing capacity. For investors, the implication is to become informed about the broader ecosystem behind it.
The firm's vision is ambitious because it reaches beyond the conventional boundaries of wealth management. It asks whether investment advice can simultaneously help an individual family build financial security, help the next generation inherit greater knowledge alongside greater assets, and direct some economic resources toward entrepreneurship and community development.
 Delivering on that vision also requires trust in the fundamentals of the client relationship. Winston says compliance is an ongoing responsibility, from understanding a client's circumstances and ensuring recommendations remain appropriate to maintaining transparent fees, accurate documentation and appropriate disclosures. Cybersecurity and protection of sensitive client information are similarly central, with secure communications, access controls, employee awareness and incident preparedness forming part of the firm's responsibility to clients.
Joseph Wealth Management's most distinctive asset is an attempt to expand financial participation itself: helping individuals build wealth, helping families preserve it, and helping communities develop the knowledge and resources to shape their own economic future.
