A featured contribution from Leadership Perspectives , a curated forum for banking, financial services, and fintech leaders, nominated by our subscribers and vetted by the Financial Services Review Editorial Board.

Queensborough National Bank & Trust and Queensborough Investments
The Human Side of Wealth: Aligning Financial Decisions with Personal Values
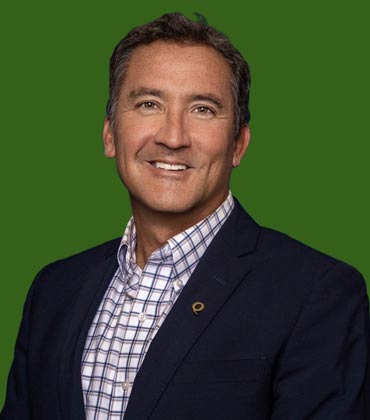
Dagan J. Sharpe
Dagan J. Sharpe is Head of Wealth Management and Executive Vice President at Queensborough National Bank & Trust and Queensborough Investments, where he leads the bank’s investment and trust divisions. Previously, he held senior leadership roles at Wells Fargo’s Private Bank and Wells Fargo/Wachovia. A certified Behavioral Finance professional, Dagan holds degrees from Arizona State University and the University of Georgia. He has authored four books and speaks on communication, values, and relational leadership.
Our financial decisions are rarely driven by numbers alone. They are influenced by personal experiences, family histories, fears, desires, and deeply held beliefs about what money represents. Understanding these influences creates an opportunity to make financial decisions that support not only our financial well-being but also our overall quality of life.
I will never forget a conversation with a successful businessman who shared how much he wished he had understood this sooner. As he said, it took several failed relationships and multiple heart surgeries to recognize the motivations driving his financial pursuits, often at the expense of nearly everything else in his life.
Though other examples may not be as extreme, they can illustrate an important point: Understanding why we relate to money the way we do, both psychologically and emotionally, can significantly improve our financial decisions and behaviors.
When I began my career nearly thirty years ago, the psychological and relational aspects of money were rarely discussed. The financial services industry was largely transactional, numerical, and focused on strategy. Over time, however, I have witnessed countless examples of well-designed financial strategies never implemented, recommendations postponed, and emotional reactions that contradicted carefully developed plans. I have also seen individuals with substantial wealth afraid to spend, continually pursuing more security while struggling to enjoy what they had already accomplished.
“The goal is not simply to accumulate money, but to understand how our values shape what wealth really means to us, and how it can better support the lives we truly want to experience and enjoy.”
The practice of behavioral finance helps explain these patterns by examining how emotions, values, experiences, and cognitive biases influence financial decisions. Recognizing these influences is important, but the real challenge is translating that awareness into meaningful action. To help, I personally use what I call a CLEAR approach: Clarify, Listen, Engage, Align, and Respond. This simple acrostic provides a practical framework to help reduce financial stress, identify personal values, and make more deliberate financial decisions by simply taking the time to better understand why we feel and behave the way we do.
Clarify: Understand what matters most
One of the primary reasons people seek financial advice is to reduce uncertainty and stress. Developing a financial plan can help but understanding what drives our stress is an equally important starting point.
This begins with identifying our values. What matters most to us, and why? There are numerous things we can value, but it’s helpful to identify five that carry the greatest weight. This helps establish priorities.
Listen: Understand the stories behind the decisions
Money often represents more than financial security. It may symbolize independence, achievement, protection, or even personal worth. Listening with curiosity to ourselves and others helps uncover the experiences and assumptions behind those meanings.
Questions such as “What does financial independence mean to you?” or “What worries you most about your financial future?” can reveal concerns that numbers alone may never uncover.
Engage: Explore emotions and behaviors
Once concerns are understood, we can examine how emotions and cognitive biases influence our choices. A person approaching retirement may have sufficient assets but remain reluctant to spend. Rather than simply knowing the numbers support retirement, it’s helpful to explore what is driving the hesitation. Are there unaddressed fears, or past financial experiences that create a deeper need for security? Engagement creates awareness and perspective, helping turn behavioral insight into an opportunity for self-discovery. Learning how to be comfortable with both saving and spending patterns helps reinforce constructive behaviors in either category.
Align: Connect money to what matters
A financially sound plan can still be disconnected from our values. Some accumulate wealth without any real sense of joy, or their stressors and fears may even increase. Others might pursue goals shaped by family or professional expectations without considering whether those goals reflect their own priorities.
Alignment connects financial resources to the life we want to live. If someone values time with family, meaningful experiences, or flexibility in retirement, those priorities should inform financial decisions alongside investment returns and risk tolerance. This doesn’t mean abandoning financial discipline; it means defining success more holistically and in alignment with our values.
Respond: Turn awareness into action
Awareness becomes valuable when it changes behavior. Responding means translating what we have learned about ourselves into deliberate financial decisions. It helps connect long-term intentions with short-term actions and provides a structure for navigating uncertainty without treating every emotional reaction as a reason to change course.
Ultimately, managing our money effectively requires understanding how we experience money, what we value, and why certain decisions feel so difficult.
By incorporating behavioral awareness and intentional communication into our financial planning, we can reduce unnecessary stress, make better-informed decisions, and use our resources more purposefully. The goal is not simply to accumulate money, but to understand how our values shape what wealth really means to us, and how it can better support the lives we truly want to experience and enjoy.
The articles from these contributors are based on their personal expertise and viewpoints, and do not necessarily reflect the opinions of their employers or affiliated organizations.
