A featured contribution from Leadership Perspectives , a curated forum for banking, financial services, and fintech leaders, nominated by our subscribers and vetted by the Financial Services Review Editorial Board.

Fremont Bank
Exploring the Future of Faster Payment Solutions
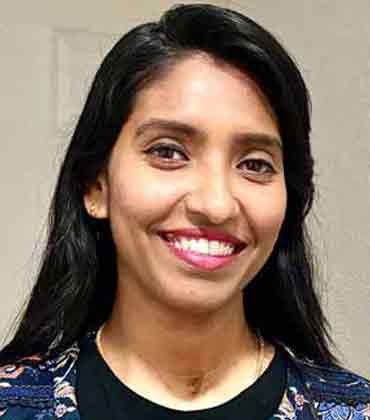
Emmelda Lawrence
In an interview with Financial Services Review, Emmelda Lawrence, Manager, Digital Commercial Banking - Cash Management/Treasury Solutions at Fremont Bank, explores the role of faster payment solutions in enhancing the agility and responsiveness of businesses within the fastpaced market.
Emmelda Lawrence is a professional in the banking and finance industry, with 10 years of experience in product management, project management, and business analysis.
She is currently working as a Commercial Banking Cash Management & Treasury Solutions Manager, Digital at Fremont Bank, where she leads the development and implementation of digital solutions for commercial clients. She has a Master of Management degree from University College Dublin and a Certified Scrum Master credential from Scrum Alliance.
In this interview she delves into the impact of technological advancements, the shift towards digital payments, and the challenges faced in the financial industry, particularly related to underdeveloped infrastructure, fraud prevention, and meeting the diverse values of different generations. Lawrence also highlights the exciting innovations on the horizon, particularly in data security and the integration of machine learning and AI in the financial sector.
Additionally, the session includes valuable advice for professionals in similar roles in the financial sector, emphasizing the importance of customer-centric solutions and the need to avoid the pitfalls of martyrdom in leadership.
In what ways can faster payment solutions contribute to the agility and responsiveness of businesses in today’s fast-paced market?
Navigating the contemporary business landscape, I find it imperative to acknowledge the prevailing characteristics and expectations that define success. In this age of startups, technology takes center stage, often spearheaded by the dynamic Gen X and Millennial cohorts.
The focus is on serving the tech-savvy Gen X, Millennial, and Gen Z demographics, aligning with the standards set by Facebook, Apple, Amazon, Netflix and Google (FAANG) companies. The ethos of instant gratification, facilitated by digital platforms, has become the norm, rendering business models without swift services and digital engagement seemingly outdated.
Notably, the shift from traditional check payments to rapid electronic and digital transactions is reshaping the financial landscape. The COVID-19 pandemic has only accelerated this trend, eliminating the need for in-person transactions and fostering a surge in mobile payments for everything from hospital bills to school fees.
In adapting to these transformative forces, it is evident that embracing digitization and meeting the expectations of seamless, rapid services are keys to remaining relevant in today's ever-evolving business environment.
What are some of the challenges in your business that current services are unable to provide an optimal solution?
In my industry, the most pressing challenge lies in the underdeveloped infrastructure that fails to adequately support real-time payments for businesses. While real-time payments have gained momentum in peer-to-peer scenarios, their adoption in the commercial payment realm has been sluggish, primarily due to the escalating threat of fraud. The focus on fraud prevention tools is imperative for fin-techs and banks before further digitizing faster payments.
“In the era of faster payments, our commitment to seamless, rapid services accentuates our dedication to meeting the dynamic expectations of today's fast-paced market, ensuring sustained growth and relevance in the digital age.”
The alarming statistics from the government accountability office, with over 700 new enforcement actions and $836 million in alleged fraud, highlight the severity of the issue. Moreover, the shift towards real-time payments necessitates the capability to provide immediate customer support—a crucial aspect often viewed as a sunk cost.
Adding to the complexity, catering to the diverse values of different generations poses a formidable challenge. While baby boomers and Gen X prioritize loyalty, millennial and Gen Z value transparency and equity but lack trust in corporate organizations. As the wealth distribution transitions from boomers to younger generations, understanding and adapting to their distinct values becomes paramount. Personally, in my industry, the decline in interest rates has led to bank closures, pushing fin-techs and banks to pivot towards non-interestdriven revenue.
However, the uphill battle lies in the minimal profit margins and equivalent costs of sales and marketing compared to interest-based products. Navigating these multifaceted challenges requires a strategic and adaptable approach to ensure sustainable growth in the evolving financial landscape.
Are there specific innovations or technologies on the horizon that you are particularly excited about in the context of digital payments?
I find it truly fascinating to witness the growing emphasis on data breach prevention and privacy in both government and organizational practices. The simple act of websites seeking cookie preferences reflects a newfound commitment to safeguarding user data.
Recently, I came across a "Shark Tank" candidate who cleverly monetized customer data with explicit permission, highlighting the evolving landscape of data usage. In the realm of applications that handle data transfer between sources and destinations, it is akin to wielding a double-edged sword.
The delicate balance between leveraging data for innovation and ensuring user privacy is a challenge that excites me, especially within the dynamic landscape of fin-tech and banking. The integration of machine learning and AI in predicting user behavior within these sectors holds immense promise, not only for driving sales opportunities but also for enhancing customer retention strategies. It is an exciting era where technology is reshaping the way we navigate data and user interactions in the financial realm.
Any advice, suggestions, or warnings you would give to professionals in your similar role working in other companies in the Financial sector in terms of dos or donts?
In my role as a product manager and developer, a piece of vital advice I received was to adopt the principle of "Customer first - Bank (organization) Best." This guiding philosophy underscores the importance of prioritizing customer-centric solutions that are not only sustainable and cost-effective but also present revenue-generating opportunities for the bank. This approach ensures that our innovations align with the needs and preferences of our customers while simultaneously benefiting the organization. It is a delicate balance that requires constant attention to the evolving landscape of customer expectations.
Additionally, I have learned the importance of avoiding the trap of martyrdom in the name of leadership. Acknowledging our human need for validation has been a key insight. By giving credit where it is due and graciously accepting recognition when offered, I have found that a positive and collaborative work environment is fostered ultimately contributing to both personal and team success.
The articles from these contributors are based on their personal expertise and viewpoints, and do not necessarily reflect the opinions of their employers or affiliated organizations.
