A featured contribution from Leadership Perspectives , a curated forum for banking, financial services, and fintech leaders, nominated by our subscribers and vetted by the Financial Services Review Editorial Board.

Credit One Bank
Expanding Credit Access through Data and Decisioning
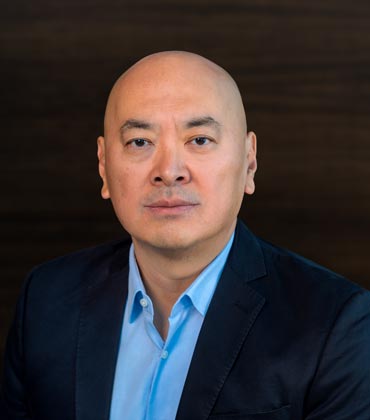
Steve Min
Steve Min is a finance leader with over 20 years of experience across financial services, credit risk and portfolio management. At Credit One Bank, he oversees the risk involved in lending decisions, combining data-driven credit strategies with a focus on compliance and customer outcomes.
Expanding Credit beyond Traditional Boundaries
Min believes that basic credit is essential to everyday activities. As an immigrant, he remembers how his parents’ first credit card helped them secure car loans and a mortgage, shaping his belief that credit can be life-changing. He focuses on consumers whom larger banks underserve because of challenged credit histories. They are often affected by unexpected life events rather than an unwillingness to repay.
53 percent of customers booked into Credit One’s card portfolio are essentially credit-invisible, with either no credit cards or only one. Its business model is designed to provide them with access to credit, education and tools to help rebuild their credit profiles.
Min combines traditional credit and behavioral data with ongoing R&D into new data sources to expand access to credit. Credit One expanded its credit profile to serve these higher-risk consumers, accepting some portfolio trade-offs to grow the market. Despite serving them, its loss rates are less volatile than those of prime borrowers.
Moving Beyond Linear Risk Models
According to Min, one of the challenges in modern credit decisioning is balancing newer modeling techniques with traditional principles, particularly the expectation that relationships between attributes and risk should be linear. More advanced techniques recognize that these relationships can be nonlinear and can change direction across different ranges.
These techniques also reveal interaction effects, where individual attributes may have limited predictive value but become meaningful when considered together. Advances in technology and computational power made it possible to identify these complex relationships. Machine-learning methods like XGBoost and Random Forest have also become increasingly common in credit decisioning.
“Our goal is to try to help people rehabilitate from some of those unexpected life emergencies, as well as for them to build their credit profile over time.”
Min applies these models across Credit One’s decisioning processes. Although regulatory uncertainty initially created challenges, many of those have been overcome. The focus is now on combining models and attributes, incorporating additional information to make accurate credit decisions. He believes the industry will move toward more precise credit decisions about who to lend to and how much to lend and charge.
Min also examines customer behavior, including ‘micro events’ and account-usage changes that may signal financial stress. Accounts with the same credit score can perform differently depending on factors such as autopay, while transaction patterns determine strategies and credit amounts.
Leading through Collaboration
Min believes empowering people is essential to effective leadership. At Credit One, he empowers risk teams to decide who to lend to and how much to lend, rather than pushing decisions upward.
For Min, long-term professional success comes down to collaboration, capability and intellectual curiosity. As professionals become more senior, he believes the how becomes increasingly important because it differentiates people, builds their professional reputation and helps them move across an organization. Intellectual curiosity and capability, meanwhile, help them solve problems and remain effective.
Advice for Emerging Finance Leaders
Min believes career growth should be viewed as a career lattice rather than a ladder. Growth can mean moving up, down or in different directions. The key is to continually look for opportunities to develop new skills, stepping outside your comfort zone.
He deliberately pursued roles outside his comfort zone to broaden his skills and perspective. His experience managing fraud taught him to work within an area marked by urgency and emotion, while a marketing role gave him a broader understanding of how the business and P&L operate. Together, those experiences helped him become a more well-rounded leader within financial services.
The articles from these contributors are based on their personal expertise and viewpoints, and do not necessarily reflect the opinions of their employers or affiliated organizations.
